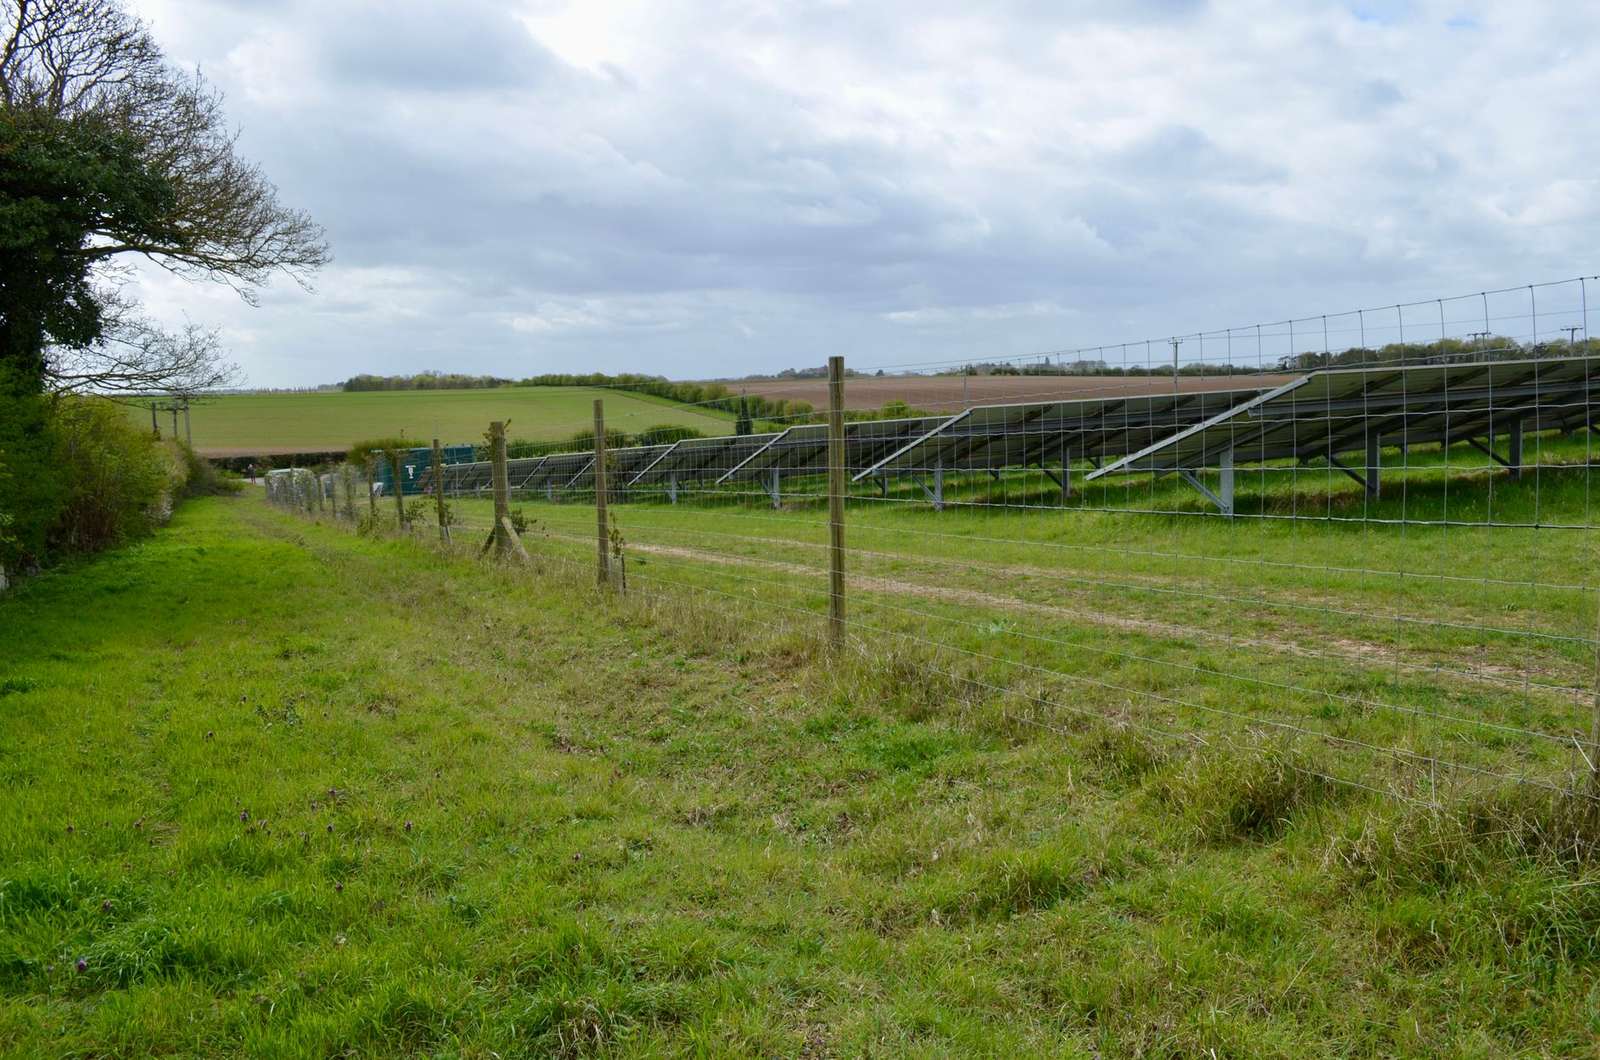
Solar energy in France is growing fast: installed solar capacity overtook hydroelectric capacity in 2025. The national plan now sets a solar PV target of 48 gigawatts by 2030.
France is one of the largest electricity markets in the region, and its solar story differs from its neighbours because nuclear power dominates the generation mix. For the wider picture across the continent, see the overview of solar energy in europe.
| Item | What to know |
|---|---|
| Solar capacity, end of 2025 | 30.4 GW, overtaking hydroelectric capacity in 2025 |
| Solar growth in 2025 | Capacity continued to grow at a high rate (+5.9 GW) |
| Negative price hours | 513 hours in 2025, compared with 352 in 2024 |
| 2030 solar target | A solar PV capacity target of 48 gigawatts by 2030 |
| Earlier draft target | A March 2025 draft forecast 54GW by 2030 |
| Annual solar auction | Capacity set at approximately 2.9GW for solar PV |
Figures come from RTE’s annual review and IndexBox’s roadmap summary; this information can change, so check the sources for the latest numbers.
How much solar capacity France has built
The French grid operator RTE reports in its annual review that the electricity generating fleet in mainland France reached 164.5 GW at the end of 2025. Within that fleet, solar photovoltaic capacity continued to grow at a high rate (+5.9 GW) during the year, which made it the main driver of fleet growth. The same review states that installed solar capacity of 30.4 GW overtook hydroelectric capacity of 25.7 GW in 2025, a symbolic change for a country whose renewable story long rested on dams.
Solar output rose in step with capacity. RTE notes that solar (+8.1 TWh) and wind (+2.8 TWh) power continued to increase, primarily as a result of growth in the solar and offshore wind fleet together with improved sunshine conditions. In other words, two things lifted production at once: more panels in the field and a sunnier year. Analysts who compare years should keep both effects apart, because a bright year can flatter the underlying growth rate.
The installed base is a mix of rooftop systems on homes and commercial buildings and ground-mounted plants. Each segment follows its own support route, which is why national totals can move differently from the headline policy targets.
The national target: PPE3 and the 2030 goal
France sets its long-term energy direction through a multiannual energy programme known by its French initials, PPE. The third edition, PPE3, covers the coming decade. According to an industry news summary, the roadmap sets a solar PV capacity target of 48 gigawatts by 2030, and the target for 2035 has been set between 55 and 80GW.
The figure is lower than earlier drafts. The same report explains that the final target is lower than a draft from March 2025, which forecast 54GW by 2030. That draft was itself a reduction from earlier proposals, so the direction of travel in the planning documents has been downward even as installed capacity kept rising.
What the lower target means in practice is set out in the same source: France had installed nearly 30GW of solar PV by the end of 2025, meaning the new 2030 target implies an average annual addition of 4.5GW of capacity. Because the 2025 build rate was above that average, the target does not require the market to accelerate. It asks the sector to hold a steady pace, which is why the French renewable energy trade body described it as a level that corresponds to a market slowdown but avoids bringing the industry to a standstill.
How solar is procured: tenders and rooftop programmes
Much of the large-scale capacity in France is awarded through competitive tenders run by the state rather than through open-ended feed-in tariffs. The roadmap coverage reports that the annual auction capacity for solar PV will be set at approximately 2.9GW and that a 300-megawatt tender for commercial rooftop solar will be launched soon. Tenders let the government steer volumes, technology mix and location, and they give developers a price signal before they commit capital.
Smaller systems follow different rules, with simplified support for household and small commercial rooftops. The split matters for planning: ground-mounted plants face land-use debates and permitting timelines, while rooftop projects face installer capacity and grid connection queues. Industry groups have repeatedly argued that tender calls need to be relaunched quickly across every segment so developers can plan pipelines with confidence.
Industrial policy is part of the picture too. According to the same coverage, the government expects the PPE3 solar targets to enable more than 38,000 jobs in the solar PV industry by 2030, and it links the plan to the emergence of module and cell factories on French soil. Whether that manufacturing materialises depends on module prices, European trade policy and the demand certainty the tenders provide.
Market effects: negative prices and curtailment
As solar grows, midday electricity prices fall. RTE counts 513 hours of negative prices in 2025 compared with 352 in 2024. The review describes how the mid-day plateau in demand has become a trough, a result of lower consumption combined with the growth of solar generation in France and across Europe. For project owners, negative hours mean that a plant selling at market prices earns nothing, or pays, during the sunniest periods.
The response has been more flexible operation. RTE reports that modulation of solar and wind farms during negative spot prices doubled in volume, reaching around 3 TWh, including 1.3 TWh of onshore wind power and 1.6 TWh of solar power. Wind and solar capacity also took a bigger role in real-time balancing: participation in the balancing mechanism increased almost tenfold, reaching 5.6 GW by the end of 2025.
These developments matter for the economics of new projects. Operators increasingly pair solar with storage, adjust contract structures and accept controlled reductions of output when prices turn negative. Readers interested in the operational side can compare this with how solar energy in spain faces a similar midday price squeeze, and how neighbouring solar energy in austria grows from a smaller base under a different support scheme.
France in the European context
France’s national goal sits inside an EU framework. The European Commission’s solar strategy set the objective to deliver over 320 GW of solar photovoltaic by 2025, which the EU surpassed, and at least 600 GW by 2030. France contributes a smaller share of that total than some larger solar markets, because its nuclear fleet already supplies a large amount of low-carbon electricity and reduces the pressure to build quickly.
That structure explains the national debate. Nuclear and solar compete for the same midday and shoulder hours in some seasons, and nuclear plants modulate their output downward when solar is abundant. Planning documents therefore weigh solar growth against grid flexibility, storage and electrification of demand such as transport, heating and data centres.
For project developers, investors and analysts, the practical lessons are consistent. Capacity additions are healthy, targets are lower than earlier drafts, price signals at midday are weakening, and flexibility is becoming a core requirement rather than an extra. Operations teams must treat curtailment, balancing market participation and grid connection constraints as everyday inputs when they forecast revenue.
What to watch next
Several threads will decide how the French solar market develops. The first is the pace of tenders: if the planned annual volumes are delivered on schedule, developers gain visibility, and if rounds slip, the pipeline thins. The second is the grid: connection queues and local network reinforcement determine how fast approved projects actually reach commercial operation. The third is the price environment, because more negative hours push developers toward storage, hybrid sites and contracts that do not depend on every hour being profitable.
The fourth is policy stability. The history of lowered targets, from earlier drafts to the final programme, shows how quickly planning assumptions can change. Developers and equipment suppliers benefit from clear, durable rules, and the next review of the programme will indicate whether the long-range goal for the following decade remains realistic. Finally, the interaction with nuclear and demand growth will keep shaping how much solar the grid can absorb without large volumes of curtailed output.
Frequently asked questions
How much solar capacity does France have?
Show answer
RTE’s annual review reports 30.4 GW of installed solar capacity at the end of 2025, ahead of the country’s hydroelectric capacity.
What is France’s solar target for 2030?
Show answer
The multiannual energy programme PPE3 sets a solar PV capacity target of 48 gigawatts by 2030, below the earlier draft figure.
Why do negative electricity prices matter for solar plants?
Show answer
When prices fall below zero, plants selling at market prices lose revenue, so operators reduce output or add storage. RTE recorded 513 hours of negative prices in 2025.
How are large solar plants awarded in France?
Show answer
Large plants are mainly awarded through state tenders. The government plans annual auction capacity of approximately 2.9GW for solar PV.