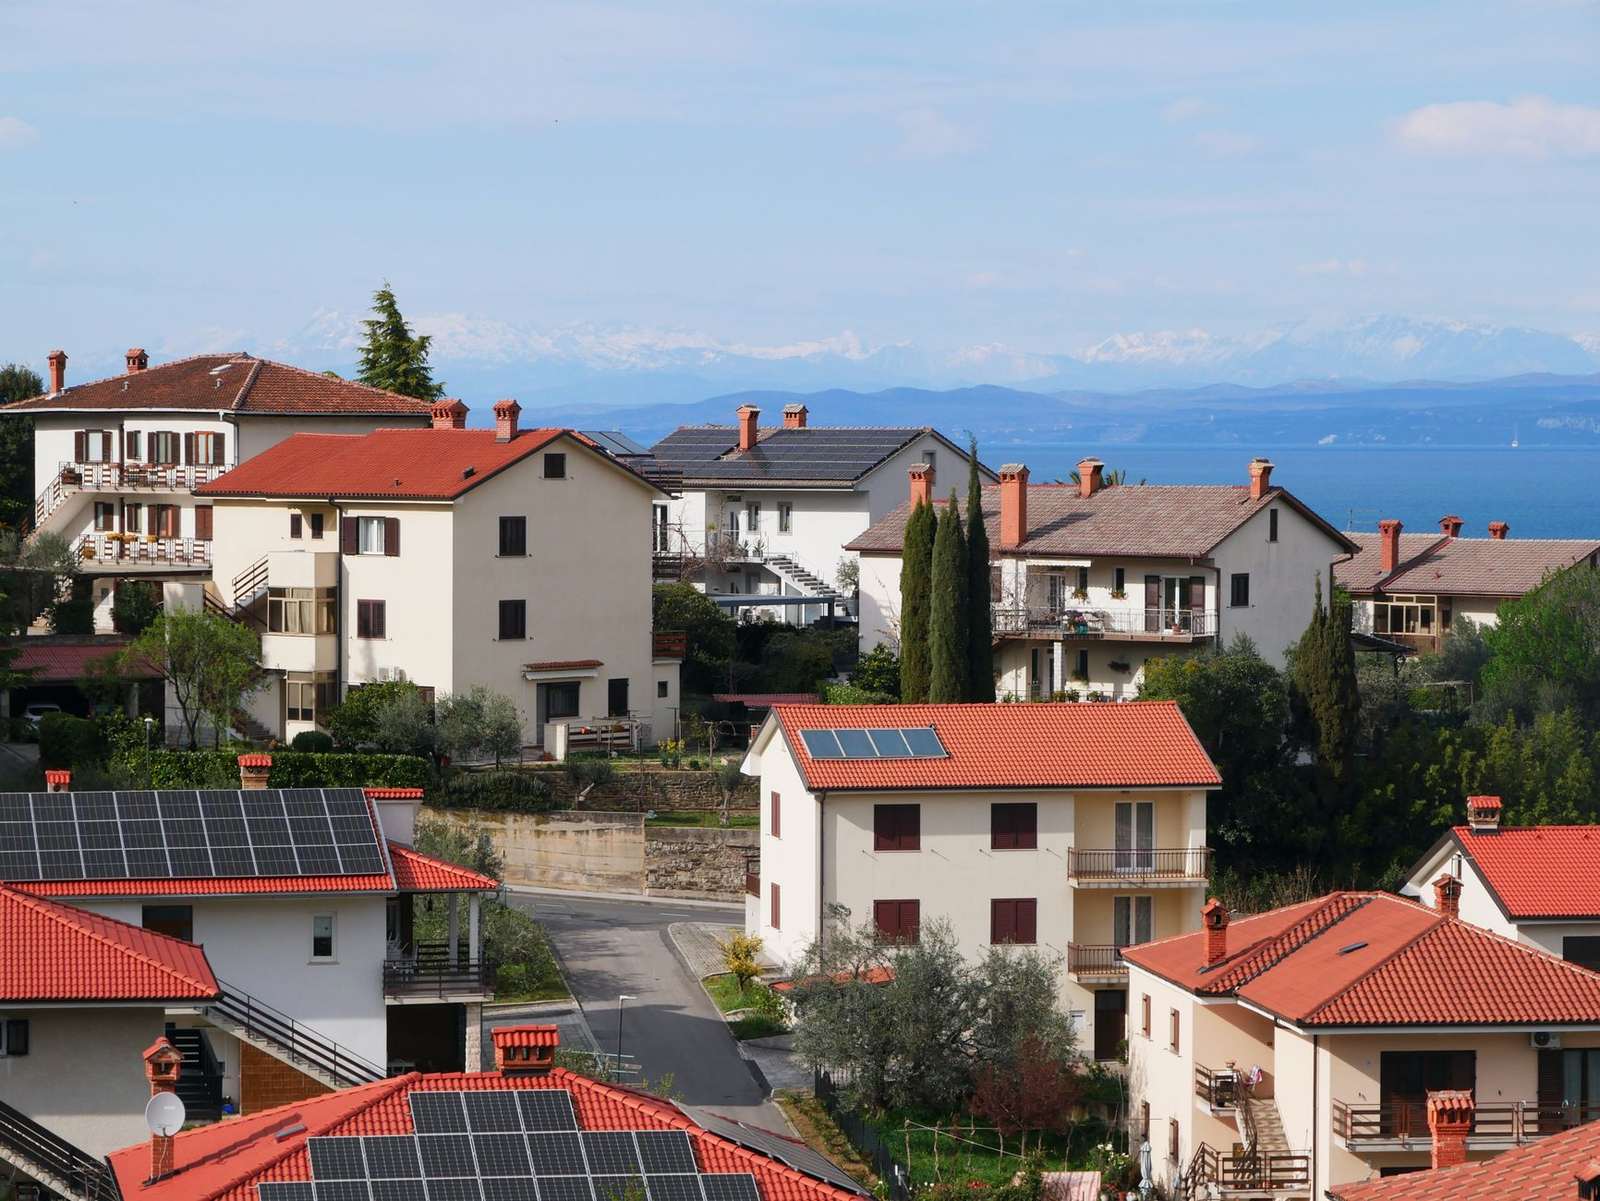
Solar energy in Europe has grown from a niche technology into the continent’s fastest-growing power source, supplying a double-digit share of electricity across the European Union and reshaping how grids, markets and policy work.
This guide covers installed capacity, the market slowdown, the leading countries, the policy framework and the operational challenges ahead.
| Key fact | Detail |
|---|---|
| EU solar installations, 2025 vs 2024 | A slight 0.7% contraction from 2024 |
| Residential share of new EU capacity | 28% in 2023, only 14% in 2025 |
| Solar share of Europe’s electricity | 13% was solar powered in 2025 |
| Solar farms’ share of installed solar capacity | Over 50%, a first |
| France’s 2025 solar capacity installed | Third-largest, overtaking Italy |
| EU’s largest solar markets | Germany and Spain maintained their leads |
Figures from www.solarpowereurope.org; they can change, so check the source before you rely on them.
How much solar power does the EU produce?
Solar photovoltaics now sit at the centre of the EU’s electricity system. According to SolarPower Europe, 13% of Europe’s electricity was solar powered in 2025, and in June solar provided the most power of any source in the bloc. The European Commission’s solar energy page reports the same milestone from Eurostat data: June 2025 was the first month in history where solar energy was the main source of electricity generated in the EU at 22%.
Within the renewable mix, the weight of solar keeps rising. The Commission states that in 2025, 47.3% of the electricity generated in the EU came from renewables and 27.5% of renewable electricity came from solar energy. Eurostat’s renewable energy statistics put the trend in historical context: solar photovoltaic power is the fastest-growing source, rising from just 7.4 terawatt hours (TWh) in 2008 to 304 TWh in 2024. Wind and hydropower still account for most renewable electricity, but solar made up 23.4% of it in the latest detailed data, the largest single block after those two.
Renewables overall are now close to half of the electricity mix. Eurostat reports that in 2025, renewable energy sources made up 49.9% of gross electricity consumption in the EU, with Austria at 90.8% among the leaders. That figure covers wind, hydropower, biofuels and solar together, so solar is one contributor to a wider shift. The broader context for all renewable technologies is covered in the renewable energy guide, which explains how the main sources compare.
Capacity and generation are different measures, and the gap between them explains why solar’s share of electricity can lag behind its share of installed power. A solar plant produces only in daylight and at a fraction of its nameplate rating over a year, while a gas or hydropower plant can run whenever it is needed. A fleet measured in gigawatts therefore yields fewer terawatt hours than the same gigawatts of dispatchable plants, and this is one reason solar output varies so strongly between summer and winter months across the continent.
Installed capacity and the 2025 milestone
Capacity is the other way to measure solar. The EU Solar Strategy set a goal for the middle of the decade, and the market outlook from SolarPower Europe shows it was met. In the words of the association, the EU has reached its 2025 solar installation target of 400 GW, with a total fleet of 406 GW. The press release adds that annual installations were 65.1 GW in 2025.
The same release marks a turning point. It describes 2025 as the first year since 2016 where the EU installed less solar than the year before, because the 65.1 GW installed in 2025 compares with 65.6 GW in 2024. The decline is small in percentage terms, only 0.7%, but it ends a long run of annual growth and changes the outlook for the end of the decade.
| Indicator | Figure |
|---|---|
| New EU solar capacity installed in 2024 | 65.6 GW |
| New EU solar capacity installed in 2025 | 65.1 GW |
| Total EU solar fleet at the end of 2025 | 406 GW |
| EU 2025 installation target | 400 GW |
| EU 2030 target (DC basis) | 750 GW |
| Most-likely 2030 outcome | 718 GW |
The figures above come from the SolarPower Europe press release on the EU Solar Market Outlook.
DC and AC capacity: why the targets differ
Readers comparing sources will find different headline targets, and the reason is the unit. SolarPower Europe notes that, as per industry standard, it expresses solar capacity in DC units, with a conversion factor of 1 GWAC = 1.25 GWDC, while the European Commission expresses its capacity in AC units. The Commission’s own page says the EU solar energy strategy set the objective to deliver over 320 GW of solar photovoltaic by 2025, which the EU surpassed, and at least 600 GW by 2030, all in alternating current. The industry figures of 400 GW and 750 GW describe the same goals measured at the panels rather than at the inverter output, so neither set of numbers contradicts the other.
Why the market is slowing
The 2025 contraction is not evenly spread. SolarPower Europe attributes it mainly to the home rooftop segment: residential solar was responsible for 28% of newly installed EU capacity in 2023, but only 14% in 2025. The release links this to an uncertain post-energy crisis environment in which rooftop support schemes were cut and household energy price pressure appeared to soften.
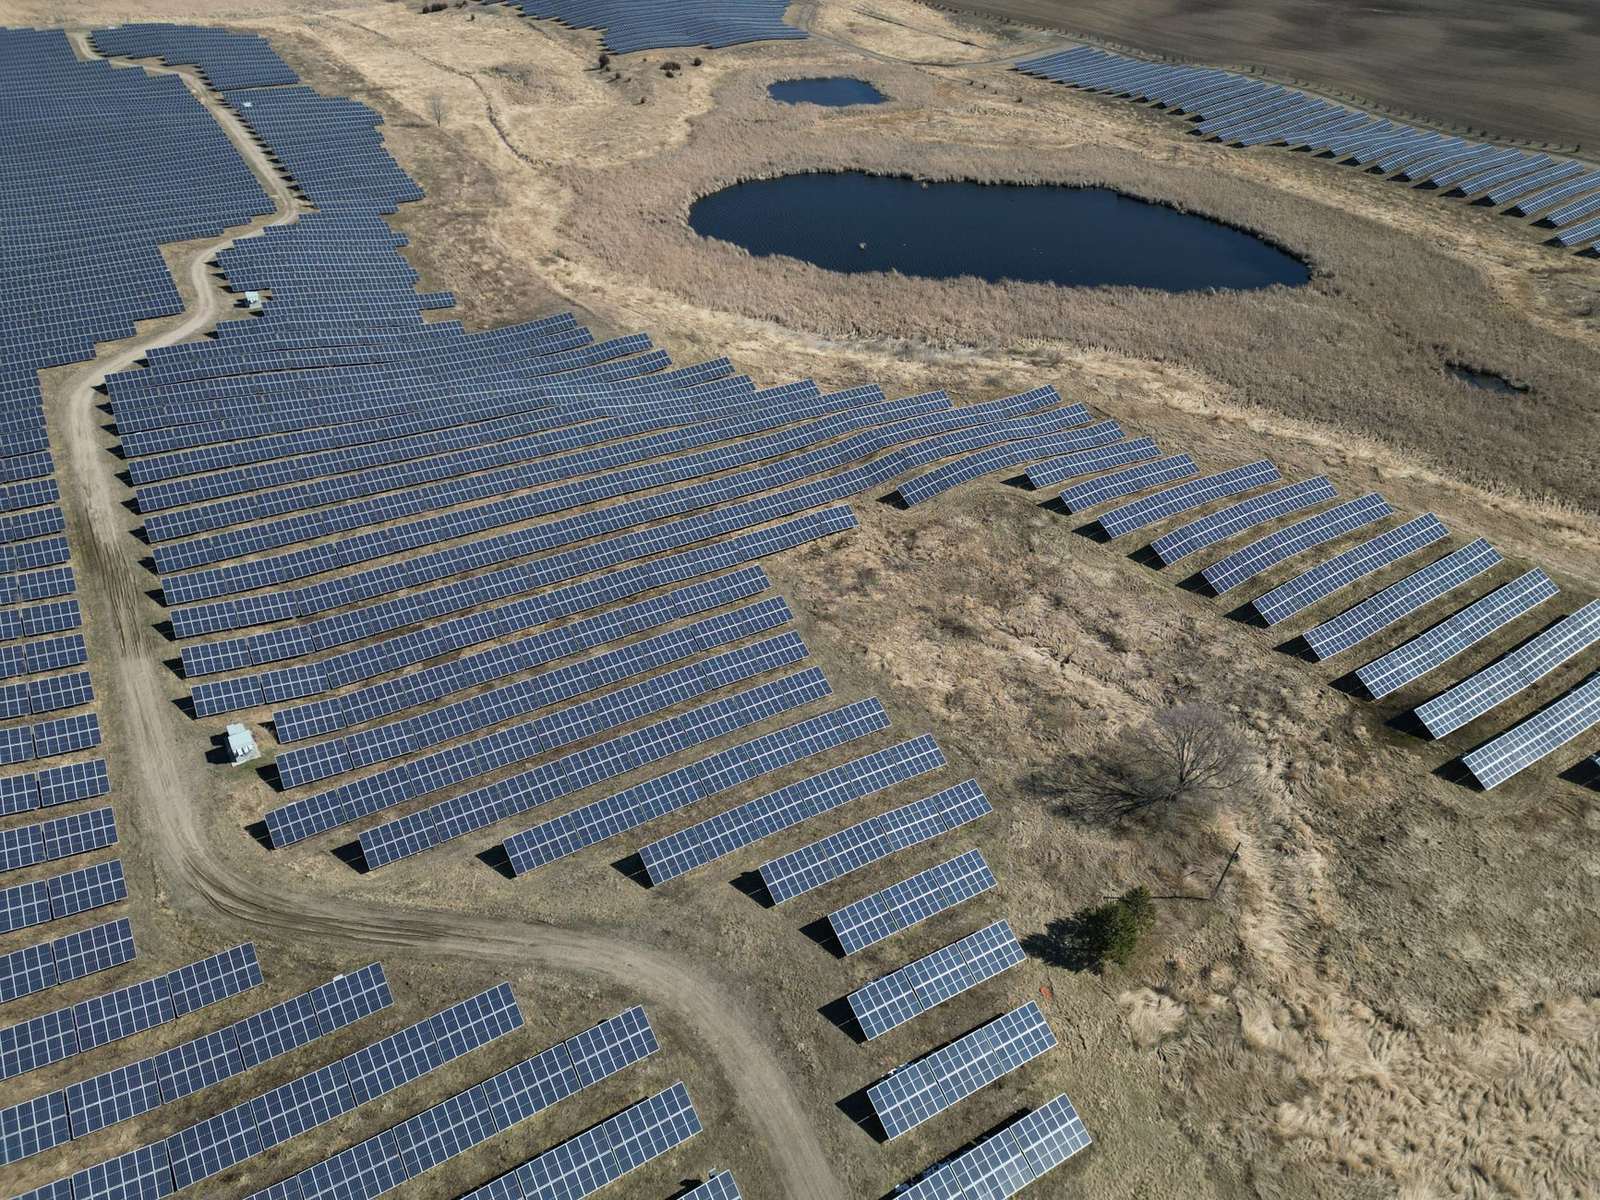
Utility-scale projects are filling part of the gap. For the first time, solar farms have made up over 50% of installed solar capacity in the EU, according to the same source. That shift changes who builds, finances and operates the fleet, as large plants rely on contracts and market revenues instead of household savings.
Rooftop, commercial and utility-scale segments
European solar is usually described in three segments, and each responds to different signals. Residential rooftops depend on retail electricity prices, on the payback households expect and on whether surplus power earns anything when exported. Commercial and industrial rooftops are driven by the desire to cut energy bills and to hedge against price swings, so they react more to corporate budgets and contract terms than to subsidies. Utility-scale plants depend on land, grid access, permits and a revenue contract, whether that is an auction award, a corporate power purchase agreement or merchant sales.
The 2025 data show how the balance moves when one segment weakens. When household demand fell, commercial and utility-scale projects kept the market close to its previous level, which is why France, with its strong commercial and utility-scale expansion, climbed the ranking while rooftop-heavy markets slipped. A market that relies on one segment is more exposed to a single policy change than one with a balanced mix.
The outlook is cautious. The release projects that the slowdown continues, with growth returning later in the decade and annual installations reaching around 67 GW. In its most-likely scenario SolarPower Europe projects that total EU solar will only reach 718 GW, short of the 750 GW target set for 2030. The association’s policy recommendations focus on redefining energy security around renewable sources, adopting a comprehensive flexibility strategy, improving permitting, boosting rooftop solar and making supply chains more resilient.
Which countries lead the European solar market?
The country ranking has been stable at the top. SolarPower Europe states that Germany and Spain maintained their leads as the EU’s largest solar markets, driven by utility-scale projects as rooftop incentives slowed. Each national market has its own rules and history, which is why the sections below point to separate country guides.
Germany has the longest history of large-scale deployment and a detailed support framework. The country profile on solar energy in Germany describes how capacity, rules and payment schemes developed there. Spain combines high irradiation with large ground-mounted projects, and the guide to solar energy in Spain covers how that market is structured.
France is the main change in the 2025 ranking. According to the release, France overtook Italy to install the third-largest solar capacity in 2025, propelled by strong commercial and utility-scale expansion, while Italy’s rooftop sector contracted sharply following the phase-out of support schemes. The French market and its targets are covered in the article on solar energy in France.
Smaller and mid-sized markets show how different the paths can be. Romania and Bulgaria entered the top 10 solar markets for the first time, with Romania boasting the fastest growth rate among its peers. The Netherlands’ ranking plunged to eighth place, mirroring its rooftop installations development, a story told in the overview of solar energy in the Netherlands, where rooftop volume and grid capacity shape the market. Austria, meanwhile, leads the EU on the share of renewable electricity at 90.8% in Eurostat’s provisional 2025 data, and its approach is described in solar energy in Austria.
The release also notes that half of the top ten markets installed less solar in 2025 than in 2024: Italy, Poland, Greece, the Netherlands and Portugal.
The policy framework behind European solar
EU policy sets the direction, and national governments design the instruments. Three layers matter most: binding renewable targets, a dedicated solar strategy and national support schemes.
Renewable energy targets and permitting rules
The legal backbone is the Renewable Energy Directive. The Commission notes that measures on permitting processes for renewable energy projects are reflected in the revised Renewable Energy Directive EU/2023/2413, and that these provisions will contribute to accelerating solar energy deployment. The binding targets and rules are explained in the guide to the EU renewable energy directive.
The EU solar strategy
The Commission adopted an EU solar energy strategy in May 2022 as part of the REPowerEU plan. It identifies remaining barriers in the sector and launched three initiatives: the European Solar Rooftops Initiative, a large-scale skills partnership and the EU Solar PV Industry Alliance. Among the rooftop measures, existing public buildings will need to have solar gradually installed from 2027, where technically, economically and functionally feasible. A closer look at the strategy and its rooftop component is in the article on the EU solar strategy.
Skills are a recurring theme. The Commission cites the EU Solar Jobs Report 2025 by SolarPower Europe, noting that Europe could see more than 900 000 solar workers by 2029, and says the European Solar Academy aims to train 100 000 workers over 3 years. A European Solar Charter signed in April 2024 by energy ministers from 23 EU countries added voluntary actions to support photovoltaic manufacturing in Europe.
From feed-in tariffs to market-based support
Early growth in Europe was driven by guaranteed payments for each kilowatt hour fed to the grid. Many countries have since moved to auctions, premiums and market sales. The history of these schemes and what replaced them is explained in the guide to feed-in tariffs in Europe. The shift matters because plants that sell at market prices carry price risk, which is exactly where the current pressure on standalone solar arises.
Operating challenges: prices, flexibility and plant performance
As solar grows, its output pattern shapes prices. SolarPower Europe observes that standalone solar faces increasing challenges on profitability, with increasing numbers of negative pricing hours eating away at revenues from solar electricity. Because panels in one region tend to produce at the same time, midday supply can exceed demand, which pushes wholesale prices down and makes flexible resources valuable.
That is why the association’s recommendations stress energy storage and system flexibility. A plant that can shift output, or a grid that can absorb it, reduces curtailment and protects revenue. Operators also depend on good operation and maintenance to keep availability and yield high over decades. The topic is covered in the hub on solar O&M services, which describes what maintenance contracts and monitoring typically include.
Grid connection and permitting
Building a plant is often faster than connecting it. Grid operators must reinforce lines and substations, and queues for connection can delay projects for years in congested regions. Permitting adds another bottleneck, because a ground-mounted plant may need land-use approval, environmental assessment and local consent before construction begins. This is why the policy recommendations from SolarPower Europe name permitting procedures directly, and why the Commission’s permitting measures sit inside the revised Renewable Energy Directive.
Rooftop systems face a different version of the same issue. Where many households in one district add panels, local low-voltage networks can reach their hosting limits, and network operators may limit new connections or require inverters to reduce output at certain times. The Dutch case, covered in the country guide above, is the clearest European example of rooftop growth meeting grid limits.
Storage and flexibility
Flexibility is the practical answer to negative prices and congested grids. Batteries charge when solar output is high and discharge in the evening, flexible demand shifts consumption toward sunny hours, and interconnectors move surplus power across borders. A solar plant combined with storage can sell power when prices recover instead of when every neighbouring plant is also producing. Such flexibility also reduces how often grid operators must order a plant to curtail its output.
Manufacturing and supply chains
Europe installs far more panels than it produces, and policymakers have treated this as a security question since the energy crisis. The Commission’s industrial measures, including the EU Solar PV Industry Alliance launched on 9 December 2022 and the European Solar Charter, aim to diversify supply chains, retain more value in Europe and deliver efficient and sustainable solar PV products, as the Commission describes them. It also points to research on new cell types, such as the PERTPV project, in which perovskite-based materials were used to build a new type of solar cell. How much of the supply chain returns to Europe will depend on cost competitiveness as well as on policy support.
For investors and grid planners, the picture is therefore mixed. The fleet is large and the technology is mature, yet the next phase of growth depends less on module cost and more on permitting speed, grid connections, flexibility and a stable revenue framework. Residential demand, which drove much of the early boom, now needs new incentives or lower energy price pressure to recover, while utility-scale growth needs revenue models that cope with low-price hours.
What to watch next
Four indicators will show whether Europe returns to faster growth. The first is the rooftop segment, where retail prices and export rules decide whether households keep investing. The second is permitting speed, which determines how quickly ground-mounted pipelines turn into operating plants. The third is the frequency of negative-price hours, which signals how well flexibility is keeping pace with solar output. The fourth is the policy response to the 2030 gap: the most-likely forecast sits below the target, so governments may adjust support, grid investment or permitting rules during the next few years. Readers following the topic can use the country guides above to see how each national market is responding.
Frequently asked questions
How much solar capacity does the EU have?
Show answer
SolarPower Europe estimates a total fleet of 406 GW at the end of 2025, after 65.1 GW of new installations during the year.
Did the EU meet its 2025 solar target?
Show answer
Yes. SolarPower Europe states that the EU has reached its 2025 solar installation target of 400 GW. On the Commission’s AC basis, the EU also surpassed its objective of over 320 GW by 2025.
Will the EU reach its 2030 solar target?
Show answer
SolarPower Europe’s most-likely scenario reaches 718 GW against the 750 GW target, so the goal is described as slipping out of reach unless policies and the rooftop market improve.
Which countries install the most solar in Europe?
Show answer
Germany and Spain lead the EU market, and France overtook Italy to take third place in 2025, according to SolarPower Europe.
Why did the residential solar segment shrink?
Show answer
The release cites cuts to rooftop support schemes and softer household energy price pressure after the energy crisis, with the segment falling to only 14% of new capacity in 2025 after 28% in 2023.